
Businesses are moving from relationship-based trust to evidence-based trust, and that shift is redefining how growth opportunities are won.
Credibility Is Demonstrated, Not Claimed
AI initiatives anchored in technology for its own sake tend to produce results that are difficult to measure and harder to sustain. Industry analysis of AI in banking points to a consistent pattern. Leading institutions anchor AI initiatives in clear business outcomes and involve business leaders from the outset, rather than leaving isolated use cases to independent technology teams.
This distinction matters in financial services because the sector operates across functions where AI's relevance is real but only if the business context shapes the design. Technology teams building in isolation from the problems they are meant to solve tend to produce pilots that work in controlled conditions, but struggle to move the metrics that boards and executives are watching.
Credibility Is Demonstrated, Not Claimed
Most businesses believe they are credible. Ask almost any business owner whether customers trust their company and the answer is likely to be yes. They have delivered projects, retained clients and grown significantly. From their perspective, credibility has already been established. But the market may reach a different conclusion.
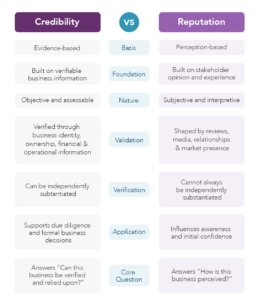
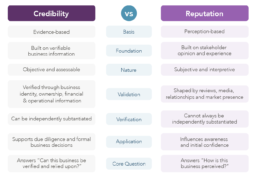
Credibility is often mistaken for reputation. They are related but not the same. Reputation is formed by what people think they know about a business. On the other hand, credibility begins when those perceptions can be tested against evidence. The difference is rarely explained.
More often, credibility reflects how easily another organisation can understand what the business is and how it operates. This is where many businesses encounter an invisible barrier.
The Rise of Evidence-Based Decision-Making
One of the most significant developments in modern commerce is the expansion of due diligence beyond regulated industries. What was once largely confined to mergers and acquisitions or highly regulated sectors has become a standard component of everyday commercial decision-making.
PwC’s 2024 Trust Survey highlights how differently trust can be perceived by businesses and their stakeholders. While 90% of executives believed their customers highly trusted their companies, only 30% of consumers reported high levels of trust in the companies they engage with.
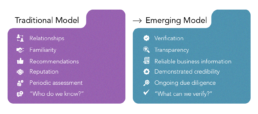
Procurement teams evaluate suppliers before onboarding them. Financial institutions assess business resilience before extending credit. Investors seek greater transparency into ownership structures, governance and operational performance before allocating capital. Large enterprises increasingly screen third parties throughout the lifecycle of a commercial relationship rather than only at the point of engagement. These practices reflect a broader shift towards evidence-based decision-making, where commercial confidence is built on reliable and verifiable information rather than relationships or familiarity.
This trend is also being reinforced by regulation. Around 84% of Organisation for Economic Co-operation and Development (OECD) member countries have introduced legislation or regulatory expectations related to corporate due diligence, while due diligence requirements now influence economies representing approximately 55% of global GDP. Verification is therefore no longer solely a matter of good governance.
Evidence does not simply confirm credibility. It can change the economics of a transaction by reducing the information gap between a business and the organisation assessing it.
The Cost of Uncertainty
When businesses lose opportunities, the assumption is often that they were outperformed on price, product or service. In reality, uncertainty can be just as significant.
Incomplete information or inconsistent business records introduce friction into commercial decisions. The more time stakeholders spend validating a business, the more likely decisions are delayed or redirected towards organisations that are easier to assess. In an increasingly competitive environment, reducing uncertainty has become a competitive advantage.
Forward-looking organisations are responding by treating business transparency and verification as strategic priorities rather than administrative exercises. They recognise that credibility should not be assembled only when financing is required. Instead, it should be embedded into the way the business presents itself every day.
Credibility as a Growth Enabler
The World Bank identifies information asymmetry as a significant constraint on business financing. Its research finds that improving the availability of accurate and meaningful business information enables more fact-based assessment and can improve access to finance. When reliable information is limited, uncertainty increases and decision-makers tend to price that uncertainty into their assessment of risk. Greater transparency and access to credible information can reduce this information gap, allowing businesses to be assessed on a clearer and more consistent basis.
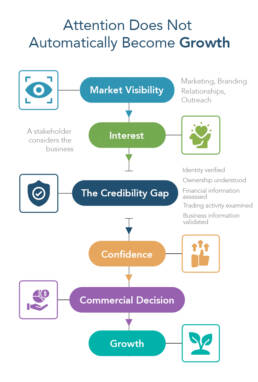
Growth strategies usually concentrate on winning attention. Companies invest in marketing and brand development because these activities create opportunities. They are right to do so. An opportunity, however, is not the same as a decision.
Between initial interest and commercial agreement lies a period of evaluation. It is here that confidence is either reinforced or weakened. Financial information may be reviewed. Ownership details may be verified. Previous trading activity may be examined. The discussion becomes less about what the business says and more about what the evidence shows.
This is where evidence-based credibility becomes increasingly important. It affects the level of confidence with which others are willing to engage with a business. In markets where organisations have more choice and greater visibility into potential counterparties, the ability to demonstrate reliability can influence which businesses progress from consideration to commercial opportunity.
Governance That Can Keep Pace With Scale
Governance is often framed as a constraint on AI progress. In practice, the evidence points the other way. Research into enterprise AI consistently describes governance as the difference between scaling successfully and stalling out, and notes that organizations where senior leadership actively shapes AI governance tend to achieve greater business value than those that delegate it to technical teams alone.
In a regulated industry like banking, governance cannot exist as a parallel track alongside AI deployment. It needs to be woven into the risk and oversight structures that already govern the institution. Effective governance integrates with existing risk frameworks rather than functioning as a separate structure running alongside them. For financial institutions in particular, that integration is what makes broader AI adoption viable within the constraints regulators expect.
An Operating Model Built Around Adoption
Much of the discussion about AI in banking centers on what the technology can do. Less attention tends to go to whether the organizational conditions are in place for people to actually use it. Industry analysis makes the case that capturing value from AI requires the organization itself to change, not just the tools it uses, from the operating model and talent structure to data flows and tracking mechanisms.
This often means breaking down the functional silos that prevent AI tools from being used consistently across the business. Cross-functional teams and coordinated approaches to AI deployment are increasingly identified as ways institutions can track value realization and prevent the fragmentation that tends to accompany large-scale rollouts. Adoption has to be designed for.
Talent and the Human Layer
AI in financial services does not operate without people, and the gap between ambition and execution frequently shows up here. Talent shortfalls across technical and compliance roles remain a persistent challenge for financial institutions pursuing AI at scale. However, successful AI scaling goes deeper than just being a hiring question. It involves building AI fluency across the workforce, alongside maintaining active human oversight as AI takes on more of the work.
In a sector where the consequences of errors can be significant and regulatory scrutiny is constant, human judgment remains a meaningful part of how AI is deployed responsibly. This is not an argument against AI capability. It is a recognition that in financial services, how people understand and work alongside AI systems is part of what makes those systems trustworthy enough to scale.
What 2026 Is Actually Testing
The financial services industry is not short of enthusiasm for AI. What 2026 appears to be testing is something different, whether that enthusiasm is backed by the organizational conditions needed to turn AI into repeatable, trusted value.
Business alignment, data readiness, governance, operating models, and talent are not new ideas. What is new is the clarity with which current industry analysis is pointing to them as the factors that will likely determine which AI efforts in banking mature into durable capability, and which ones remain well-intentioned experiments.
Manually Vetting Vendors? Save Time, Reduce Risk, & Stay Compliant
Dun & Bradstreet’s Vend-R platform delivers verified, risk-rated vendor profiles in one place, cutting vetting time, supporting compliance standards, and helping you avoid exposure to unreliable or noncompliant suppliers.
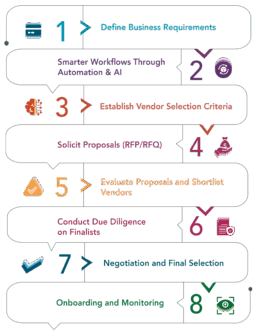
A clearly defined vendor selection process helps corporations reduce uncertainty and make informed, high stakes decisions with confidence. By following these key steps, from defining business needs to onboarding and monitoring, organizations can ensure that each vendor relationship is built on a foundation of due diligence, strategic fit, and long term value. In the next blog, we’ll explore how to optimize these processes further by embedding best practices that improve efficiency, compliance, and performance across the procurement lifecycle.